Oil and fuel supplies are being disrupted around the world right now, and it is not because of one single event. Several major energy disruptions are happening at the same time, affecting refineries, pipelines, tankers, and some of the world’s most important shipping routes.
In Russia, Ukrainian drone attacks have knocked major oil refineries offline or sharply reduced their output. Russia’s Yaroslavl refinery stopped processing crude after a September 17 drone attack damaged a primary crude-distillation unit responsible for roughly 40 percent of the refinery’s processing capacity. Another unit representing about one-third of capacity was already undergoing repairs following an August strike.
The Syzran and Saratov refineries have also halted processing following Ukrainian drone attacks. Syzran’s main crude-distillation unit, responsible for roughly 71 percent of the plant’s capacity, was heavily damaged, while its remaining crude unit was already under repair. Saratov also stopped processing following equipment damage and fires from repeated attacks. Russia has restricted exports of gasoline, diesel, and jet fuel as it deals with domestic fuel shortages.
The problem extends beyond those individual plants. Six refineries account for about half of Russia’s diesel production, and Reuters reported that half of those six had either significantly reduced output or completely halted production in September because of damage from drone attacks.
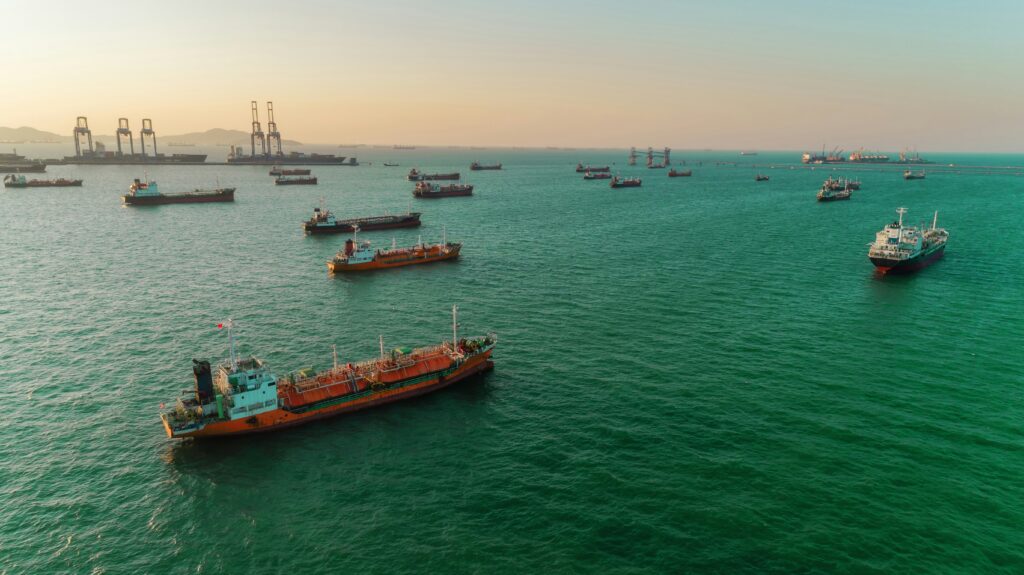
At the same time, traffic through the Strait of Hormuz has fallen sharply during the regional conflict. On September 1, two supertankers carrying Saudi crude were struck by projectiles while traveling through the strait. Each tanker had loaded roughly 2 million barrels of oil.
Saudi Arabia’s East-West pipeline became especially important because it allows Saudi oil to bypass Hormuz and move to the Red Sea. But that pipeline was also forced offline following drone attacks. It had been moving roughly 4 million barrels per day, and Reuters reported that a prolonged outage threatened flows equivalent to as much as 4 percent of global oil supply.
The pressure does not end there. Houthi advances and threats around the Bab el-Mandeb Strait have increased risks around another critical Middle Eastern shipping route. Tankers can avoid the area by sailing around Africa, but the detour can add weeks to a voyage while substantially increasing fuel and shipping costs. Tanker rates have already reached record highs.
That matters because the problem is not simply whether crude oil exists somewhere in the world. Crude has to be transported, refined, and then moved to the markets that need gasoline, diesel, jet fuel, and other petroleum products. When refineries are damaged, pipelines are disabled, and tankers are forced onto longer or more dangerous routes, every part of that system becomes more expensive and less efficient.
Diesel provides one of the clearest examples. Combined net diesel exports from Russia and the Gulf were about 1.6 million barrels per day lower in August than they had been in February. Before the conflicts intensified, Russia and the Gulf together accounted for almost 45 percent of global seaborne diesel trade. The sharp reduction in supply helped push diesel prices and refining margins to record levels.
The United States is not insulated from those pressures. U.S. refineries were already operating at extremely high utilization rates as the global fuel market tightened. For the week ending September 11, the Energy Information Administration reported U.S. refinery utilization of 96.8 percent. Midwest refinery utilization was 100 percent, leaving relatively little unused refining capacity available in the region to immediately replace production lost at a major plant.
Against that backdrop, ExxonMobil’s Joliet refinery in Illinois was forced offline following a plant-wide power outage in September. The refinery is a major supplier of gasoline and diesel to the Midwest and normally produces roughly 11 million gallons of fuel per day. Although power was restored, the refinery remained offline as Exxon assessed the facility and dealt with additional problems, including floodwater that overwhelmed a pump.
The Joliet outage did not cause the broader global increase in fuel prices. But losing a large Midwest refinery in an already tight market can add additional regional pressure, particularly when refineries are already operating near capacity. Replacing the output of a refinery processing roughly 275,000 barrels per day is not as simple as turning up production somewhere else.
There have also been other significant U.S. refinery disruptions this year. In March, an explosion and fire temporarily shut Valero’s roughly 380,000-barrel-per-day Port Arthur refinery in Texas, the company’s largest refinery. That was a separate event months before the Joliet outage, not a cause of this week’s market movement. But it illustrates how domestic refinery disruptions can compound broader supply problems when the refining system has little spare capacity.
Meanwhile, the Trump administration has pursued several policies intended to expand or secure U.S. oil supplies over the longer term.
On federal and Indian lands, the Bureau of Land Management approved 6,027 new oil and gas drilling permits between January 20 and December 31, 2025. BLM said that was 63.7 percent more than during the comparable period of the previous administration and the highest number of Applications for Permit to Drill it had approved in any year during the previous 15 years. BLM also held 22 oil and gas lease sales during 2025. Drilling permits do not translate into new barrels immediately, but they provide operators with authorization to develop federal and Indian oil and gas resources.
The administration has also been looking at ways to increase U.S. refining capacity. Reuters reported in September that the White House was considering using the Defense Production Act to support refinery expansion and improve efficiency at existing facilities. Discussions included faster permitting, regulatory changes, investment in existing plants, and potentially expanding refining capacity rather than relying entirely on the construction of new refineries. No final decision on using the law had been announced at the time of the report.
Another major part of the administration’s supply strategy involves Venezuela. In August, the United States and Venezuela announced an agreement covering 17 Venezuelan oil fields containing roughly 65 billion barrels of reserves. The White House says the agreement is intended to increase production and direct additional Venezuelan crude toward U.S. refineries, with part of the supply potentially available for the Strategic Petroleum Reserve and other U.S. needs.
Reuters reported that the arrangement could give the United States immediate access to crude from mature Venezuelan fields and could eventually support production of as much as 1.5 million barrels per day if the projects are successfully developed. U.S. producer Continental Resources has also signed an agreement with Venezuela’s state oil company to explore development of the Ayacucho 2 block in the Orinoco Belt.
The Venezuelan agreement is not an immediate solution to today’s fuel prices. Expanding production requires investment, equipment, infrastructure, and time. Reuters has also reported legal and implementation questions surrounding the agreement and uncertainty about exactly how quickly production could increase.
The disruptions affecting fuel markets today are immediate and ongoing. Russian refineries have been damaged. Diesel exports from Russia and the Gulf have fallen sharply. Traffic through the Strait of Hormuz has been severely disrupted. Saudi Arabia’s major bypass pipeline has been attacked. Shipping around the Red Sea has become more dangerous and expensive. And U.S. refineries have been operating with little spare capacity.
At the same time, actions such as approving additional drilling permits, considering ways to expand refinery capacity, and developing access to additional Venezuelan crude are aimed at increasing or securing supplies over a longer period. They cannot instantly replace millions of barrels disrupted elsewhere in the world, but they address a different part of the equation: increasing the amount of oil and refining capacity potentially available to the United States in the future.
Fuel prices are being affected by disruptions at nearly every stage of the global energy system — from crude production and refining to pipelines, tankers, and shipping chokepoints.
That is what makes the current situation a perfect storm. It is not one refinery, one pipeline, or one country. Multiple supply problems are colliding at the same time, tightening the availability of crude oil and refined fuels across interconnected global markets.